
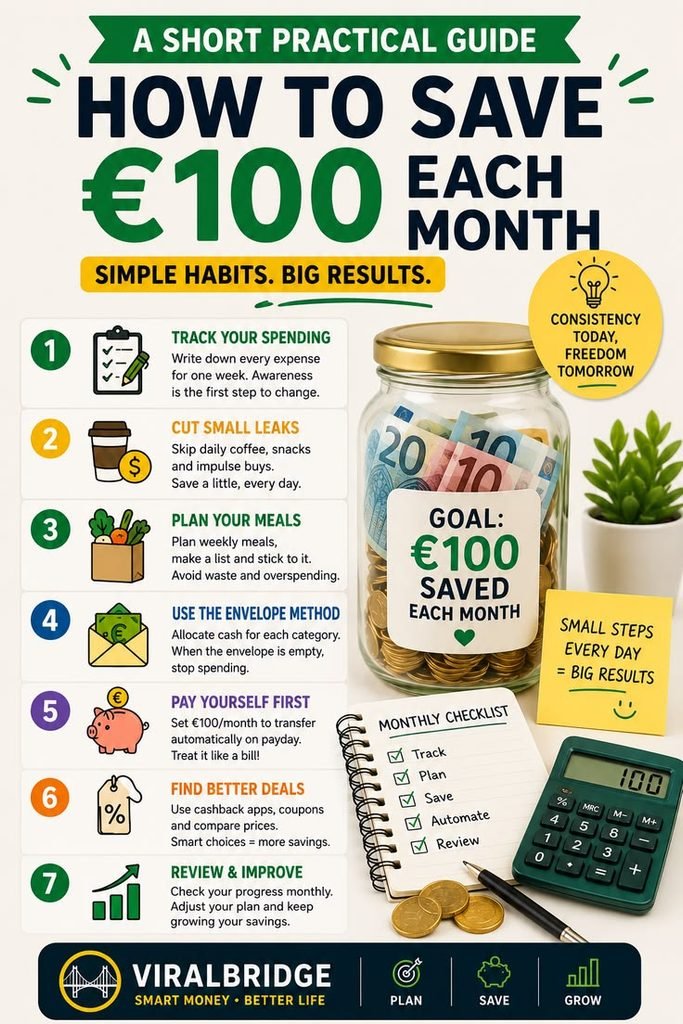
Saving money regularly is one of the most important habits you can develop for your financial future. However, many people struggle with one simple question: How much should I save each month?
There is no single savings amount that works for everyone. Your ideal monthly savings goal depends on your income, expenses, debt, financial responsibilities, and future goals. Someone earning $3,000 per month may have very different savings opportunities from someone earning $7,000 per month.
Instead of focusing on a specific dollar amount, it can be more useful to create a savings goal that fits your circumstances and can be maintained consistently.
Why Is a Monthly Savings Goal Important?
Having a specific savings goal gives your money a purpose. Without a target, it can be easy to spend your entire paycheck and postpone saving until later.
A monthly goal creates a regular habit. Even a relatively small amount can become meaningful when you contribute consistently over time.
For example, saving $200 every month would result in $2,400 in contributions over one year, before considering any interest or investment growth. Increasing that amount to $300 per month would result in $3,600 over a year.
The important point is consistency.
Is Saving 20% of Your Income a Good Goal?
You may have heard recommendations suggesting that people save around 20% of their income. This can be a useful guideline for some households, but it should not be treated as a universal rule.
Your ability to save depends on your circumstances.
If your monthly take-home pay is $4,000, saving 20% would mean setting aside $800 each month. For someone with relatively low expenses, that might be achievable.
However, someone with high housing costs, student loans, childcare expenses, or other significant obligations may not be able to save $800 every month.
The better approach is to start with an amount you can realistically maintain and increase it when your financial situation improves.
Start With What You Can Afford
If you are currently saving nothing, do not assume you need to immediately save a large percentage of your income.
Starting with $25, $50, or $100 per month can help you establish the habit.
Once your income increases or your expenses decrease, you can gradually raise your savings contribution.
For example, you might start by saving $100 each month, increase it to $150 after a few months, and eventually reach $250 or more.
A sustainable habit is generally more useful than setting an unrealistic goal that you abandon after a few weeks.
Build an Emergency Fund First
One of the most important reasons to save is to prepare for unexpected expenses.
An emergency fund can help cover costs such as vehicle repairs, unexpected medical expenses, home repairs, or a temporary loss of income.
If you have no emergency savings, building an initial cash cushion can be an important priority.
Some people aim to eventually save several months of essential living expenses. The appropriate amount depends on factors such as income stability, monthly expenses, employment situation, and family responsibilities.
Keep emergency savings in an appropriate savings account where the money is accessible when needed.
Consider Your Financial Goals
Your monthly savings goal should be connected to your goals.
You might be saving for:
- An emergency fund
- A home down payment
- A new vehicle
- Education
- Travel
- A wedding
- A business
- Retirement
- Future investments
Each goal may require a different savings strategy.
For example, suppose you want to save $6,000 for a specific purchase within one year. Ignoring interest, you would need to save an average of $500 per month.
Having a specific target makes it easier to determine whether your monthly contribution is enough.
How Much Should You Save for Retirement?
Retirement savings should also be considered when setting your monthly savings goal.
The amount you need depends on factors such as your age, income, expected retirement lifestyle, current savings, planned retirement age, and other sources of income.
If your employer offers a workplace retirement plan, review the available options and determine whether there is an employer contribution or matching program.
Starting early can give retirement savings more time to potentially grow through compounding, although investment returns are not guaranteed.
As your income changes, consider reviewing your retirement contributions and increasing them when appropriate.
Pay Off Debt or Save?
This is a common financial question.
If you have high-interest debt, you may want to balance saving with debt repayment. Maintaining some emergency savings can help prevent unexpected expenses from forcing you to take on additional debt.
At the same time, paying down expensive debt can reduce future interest costs.
The right balance depends on your interest rates, emergency savings, income stability, and other financial circumstances.
A financial plan can help you decide how much of each paycheck should go toward savings and debt repayment.
What If You Cannot Save Much?
Not everyone has enough income to save a large amount every month.
If your budget is already tight, focus first on creating a small and sustainable savings habit.
Even $20 or $50 per month can help you begin building a financial cushion.
You can also look for ways to create additional savings by reviewing recurring expenses, reducing unnecessary purchases, or directing unexpected money toward savings.
Tax refunds, bonuses, gifts, or other one-time payments can sometimes provide opportunities to increase savings without changing your regular monthly budget.
Automate Your Savings
One of the easiest ways to maintain a monthly savings goal is to automate it.
You can arrange for money to move automatically from your checking account to a savings or investment account shortly after receiving your paycheck.
Automation reduces the need to remember to save each month.
It also helps you treat savings as a regular financial priority rather than something you do only when money remains at the end of the month.
Make sure your automatic transfers are affordable and do not cause your checking account to become overdrawn.
Increase Your Savings When Your Income Rises
When your salary increases, it can be tempting to increase spending immediately.
Instead, consider directing part of the additional income toward savings.
For example, if you receive a $400 monthly increase in take-home pay, you could put $200 toward savings while using the remaining $200 for other priorities.
This approach can help your financial progress grow alongside your income without requiring you to dramatically change your lifestyle.
Review Your Savings Goal Regularly
Your savings goal should change when your circumstances change.
If you receive a raise, pay off a loan, move to a lower-cost home, or reduce your expenses, you may have more money available to save.
On the other hand, major life changes may require you to temporarily reduce your savings contribution.
Review your budget every few months and ask whether your current savings target still makes sense.
The goal is progress, not perfection.
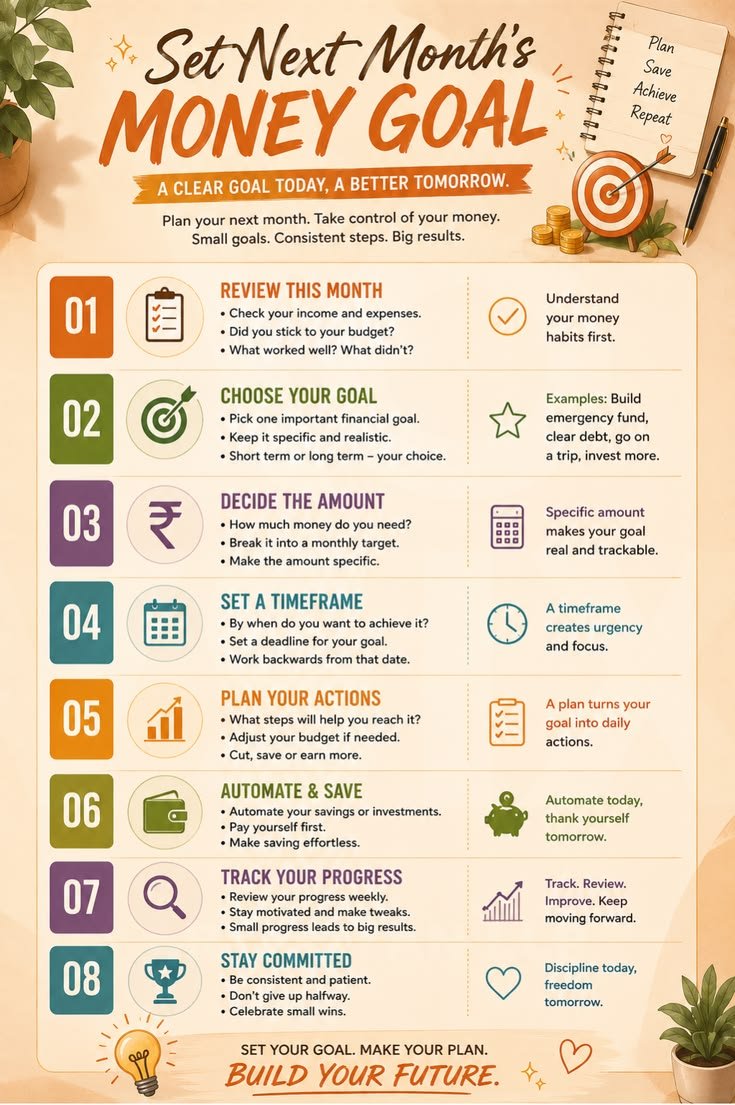
A Simple Way to Set Your Monthly Savings Goal
A practical process is to follow these steps:
Step 1: Calculate your monthly take-home income.
Step 2: List your essential expenses.
Step 3: Identify debt payments and other financial obligations.
Step 4: Determine how much you need for an emergency fund.
Step 5: Set specific short- and long-term financial goals.
Step 6: Choose a monthly savings amount that fits comfortably within your budget.
Step 7: Automate the contribution if possible.
Step 8: Review and increase your savings goal as your finances improve.
Final Thoughts
A good monthly savings goal is one that fits your financial situation and can be maintained consistently.
For some people, saving 20% of income may be realistic. For others, starting with a smaller amount may be more appropriate. The most important thing is to establish a regular savings habit and gradually increase your contributions when possible.
Start by building an emergency fund, consider your short- and long-term goals, manage debt responsibly, and include retirement savings in your broader financial plan.
There is no perfect savings number for everyone. A realistic goal that you follow consistently can be more valuable than an ambitious target that you cannot maintain.