
A credit score is one of the most important numbers in personal finance. It can affect your ability to borrow money, the interest rates you may receive, and sometimes whether you qualify for certain financial products.
For people who are new to credit, the subject can seem confusing. What exactly is a credit score? How is it calculated? What makes a score go up or down? And why does it matter?
Understanding how credit scores work can help you make more informed financial decisions and develop habits that support your long-term financial goals.
What Is a Credit Score?
A credit score is a numerical representation of information in your credit history that is designed to help lenders assess your credit risk.
In simple terms, a credit score gives lenders an indication of how you have handled credit in the past.
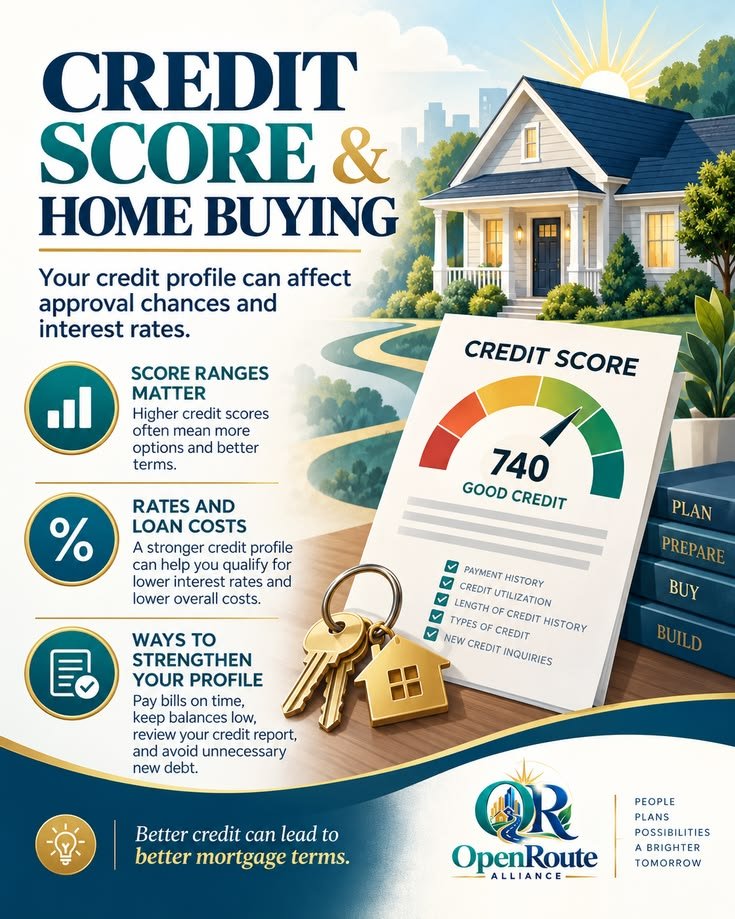
Credit scores are generally calculated using information found in your credit reports. That information can include your payment history, outstanding balances, length of credit history, and applications for new credit.
There are different credit-scoring models, so you may not have exactly the same score everywhere.
One of the most commonly known scoring systems in the United States is the FICO Score. Other scoring models, such as VantageScore, are also used.
Why Does a Credit Score Matter?
Your credit score can matter because lenders may use it when deciding whether to approve applications for credit.
For example, a lender may consider your credit score when you apply for:
- A credit card
- An auto loan
- A mortgage
- A personal loan
- Other forms of credit
A higher score does not guarantee approval, and lenders generally consider other factors as well. However, your credit score can be an important part of the application process.
How Credit Scores Are Calculated
Different credit-scoring models use different formulas, but several factors commonly play an important role.
Payment History
Your payment history refers to whether you have paid your credit obligations on time.
Late payments can negatively affect your credit profile, particularly when they are reported to credit bureaus.
Making payments on time is therefore one of the most important habits for maintaining healthy credit.
Amounts Owed
The amount of debt you owe can also affect your credit profile.
For revolving accounts such as credit cards, the relationship between your balance and credit limit is often called credit utilization.
For example, if your credit card has a $5,000 limit and you have a $1,000 balance, your utilization is 20%.
Credit utilization can be an important factor in some credit-scoring models.
Length of Credit History
The length of time you have used credit can also matter.
A longer credit history can provide more information about how you have managed credit over time.
This does not mean someone with a short credit history cannot have a strong credit score. It simply means the age and history of accounts can be relevant factors.
New Credit Applications
Applying for several new credit accounts within a short period can affect your credit profile.
Some applications result in hard inquiries, which can affect your credit score depending on the scoring model and circumstances.
This is one reason it can be helpful to apply for new credit thoughtfully rather than opening numerous accounts without a clear purpose.
Credit Mix
Credit-scoring models may also consider the types of credit you use.
For example, a credit profile might include revolving credit and installment loans.
You generally should not borrow money simply to create a particular credit mix. Taking on unnecessary debt can create financial problems.
What Is a Good Credit Score?
There is no single number that guarantees that you will receive a loan or the best possible interest rate.
Different scoring models use different ranges and categories.
For example, the commonly used FICO scoring range is 300 to 850.
Generally, higher scores indicate lower credit risk according to the scoring model, but lenders may use additional information when evaluating an application.
Your income, existing debt, employment, loan amount, and other factors may also influence a lender’s decision.
How Can You Check Your Credit Score?
You may be able to access your credit score through your bank, credit card company, credit bureau, or another financial service.
Remember that you may have multiple credit scores because different lenders and services can use different scoring models and credit-report data.
Checking your own credit information does not generally have the same effect as applying for new credit.
It is also important to review your credit reports for inaccurate or unfamiliar information.
What Is a Credit Report?
A credit report is different from a credit score.
A credit report contains information about your credit history.
A credit score is a number calculated using information from a credit report and a particular scoring model.
Credit reports can contain information about credit accounts, payment history, balances, and inquiries, among other details.
Reviewing your credit reports can help you identify errors or signs of potential identity theft.
How Can You Build a Strong Credit History?
If you are starting from scratch, building credit takes time.
One of the most important habits is paying bills on time.
If you use a credit card, consider keeping your balance manageable and making payments according to the terms of your account.
Avoid borrowing more than you can comfortably repay.
You can also monitor your credit reports and review your accounts regularly.
What If You Have No Credit History?
People who have never used credit may have limited or no credit history.
This can make it difficult to qualify for certain financial products because lenders have less information to evaluate.
Some beginners may use products designed for people building credit, such as secured credit cards.
A secured credit card typically requires a refundable security deposit, which may serve as collateral for the account.
Before opening any credit product, understand its fees, interest rate, terms, and requirements.
Can You Improve a Credit Score?
Credit scores can change over time as information in your credit reports changes.
If your credit profile has negative information, improving your credit may require patience.
Helpful habits can include:
- Paying bills on time
- Reducing high credit card balances
- Avoiding unnecessary applications for new credit
- Checking credit reports for errors
- Keeping credit accounts in good standing
- Borrowing only what you can afford to repay
There is no instant solution that guarantees a higher credit score.
Be cautious of companies that promise to quickly repair your credit for a large fee or claim they can remove accurate negative information.
Why Credit Scores Matter for Loans
One major reason credit scores matter is that they can influence the cost of borrowing.
Lenders use risk information to determine the terms they offer.
A stronger credit profile may help a borrower qualify for more favorable terms, while a weaker credit profile may result in higher costs or more limited options.
The actual terms offered depend on the lender, type of loan, market conditions, and the borrower’s overall financial profile.
Credit Scores and Everyday Financial Planning
Credit scores are only one part of your financial health.
Having a high credit score does not automatically mean you are financially secure.
Someone could have an excellent credit score while carrying significant debt.
Similarly, someone with a limited credit history may still be responsible with money.
It is therefore important to consider credit alongside savings, income, expenses, debt, emergency funds, and long-term financial goals.
Final Thoughts
A credit score is a number used to help assess credit risk, and it can play an important role in borrowing decisions.
Payment history, amounts owed, credit history, new credit, and other factors can influence credit scores depending on the scoring model.
Building strong credit generally requires consistent financial habits rather than quick fixes. Paying bills on time, managing balances responsibly, reviewing your credit reports, and avoiding unnecessary debt can help you maintain a healthier credit profile.
Most importantly, remember that your credit score is a financial tool, not a measure of your overall financial worth. Use credit carefully, understand the terms of your accounts, and focus on building financial habits that support your long-term goals.