

Your financial future is influenced by many decisions you make with your money today. While earning a higher income can help, your financial habits are also important. How you spend, save, borrow, invest, and plan your money can affect your ability to reach important financial goals.
The good news is that you do not need to make dramatic changes overnight. Small, consistent habits can gradually improve your financial situation. Whether you are starting your first job, managing a family budget, or preparing for retirement, developing healthy money habits can help you make more informed financial decisions.
Here are some money habits that can help create a stronger financial future.
1. Create and Follow a Budget
One of the most useful financial habits is creating a realistic budget. A budget helps you understand how much money you earn, how much you spend, and where your money is going.
Start by listing your regular income and expenses. Include housing, food, transportation, utilities, insurance, debt payments, entertainment, subscriptions, and savings.
Once you understand your spending patterns, you can decide whether your money is being used according to your priorities.
A budget does not mean you cannot enjoy your money. Instead, it gives you a clearer picture of what you can afford while helping you avoid unnecessary financial stress.
2. Track Your Spending
Creating a budget is useful, but tracking your actual spending can make it more effective.
Small purchases can add up over time. Coffee, restaurant meals, subscriptions, online purchases, and entertainment may seem inexpensive individually, but frequent spending can have a significant effect on your monthly budget.
Review your bank and credit card transactions regularly. You can use a spreadsheet, budgeting app, or simple notebook.
The purpose is not to feel guilty about spending. It is to understand your habits so you can make better decisions.
3. Save Money Consistently
Saving should become a regular financial habit rather than something you do only when you have extra money.
Even if you can only save a small amount, consistent contributions can help you build financial resources over time.
Consider setting a specific savings goal and making automatic transfers from your checking account to your savings account.
You can create separate goals for emergencies, travel, education, a home purchase, or other future expenses.
4. Build an Emergency Fund
An emergency fund can provide financial protection when unexpected expenses occur.
Car repairs, medical expenses, home repairs, or changes in employment can create sudden financial pressure. Without savings, people may have to rely on credit cards or loans to cover these costs.
Start with an amount that fits your circumstances and gradually build your savings. Many people aim to eventually maintain several months of essential expenses in an emergency fund.
Keep emergency savings somewhere accessible but separate from the account you use for everyday spending.
5. Avoid Unnecessary Debt
Debt can be useful when it helps you purchase something important or finance a long-term investment, but unnecessary high-cost debt can make financial progress more difficult.
Before borrowing money, consider whether the purchase is necessary and whether you can comfortably afford the payments.
Credit cards can be particularly expensive if balances are carried from month to month and interest accumulates.
Paying balances on time and understanding interest rates can help you maintain better control over your finances.
6. Pay Bills on Time
Paying bills on time is a simple but valuable money habit.
Late payments can potentially result in fees, penalties, service interruptions, and negative effects on credit history depending on the account and circumstances.
Consider setting up automatic payments or calendar reminders for recurring bills.
Before setting up automatic payments, make sure there will be enough money in the account to cover the scheduled payment.
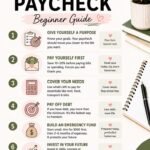
7. Save Before You Spend
A common approach to saving is to spend money throughout the month and save whatever remains. Unfortunately, there may not be much left at the end.
An alternative is to save first.
When you receive your paycheck, transfer a predetermined amount toward your savings or investment goals before spending the rest.
This approach can make saving a normal part of your financial routine.
8. Increase Your Financial Knowledge
Financial education can improve the quality of your financial decisions.
Take time to learn about budgeting, interest rates, credit scores, taxes, insurance, investing, retirement accounts, and other financial topics relevant to your situation.
You do not need to become a financial expert. Understanding basic financial concepts can help you ask better questions and recognize potentially expensive mistakes.
When making important financial decisions, use reliable information and consider professional advice when appropriate.
9. Set Specific Financial Goals
Having clear goals can make it easier to stay motivated.
Instead of saying, “I want to save more money,” create a specific objective such as saving $3,000 for an emergency fund within a certain period.
You can divide larger goals into smaller monthly or weekly targets.
Examples of financial goals include:
- Building an emergency fund
- Paying off high-interest debt
- Saving for a home
- Increasing retirement contributions
- Building an investment portfolio
- Saving for education
- Creating a travel fund
Your goals should reflect your own income, responsibilities, and priorities.
10. Review Your Subscriptions and Recurring Expenses
Recurring expenses can quietly consume a significant portion of your income.
Review your streaming services, gym memberships, software subscriptions, phone plans, insurance policies, and other recurring payments periodically.
Ask yourself whether you still use each service and whether there are less expensive alternatives.
Canceling services you no longer need can free up money that could instead be used for savings or debt repayment.
11. Think Before Making Large Purchases
Developing a habit of pausing before major purchases can protect your budget.
Instead of buying something immediately, give yourself time to consider whether you actually need it, whether you can afford it, and whether the purchase supports your financial goals.
For expensive purchases, compare prices and consider the total cost of ownership rather than only the initial price.
A short waiting period can sometimes prevent an impulse purchase.
12. Invest for Long-Term Goals
Once your basic financial foundation is in place, investing may become part of your long-term strategy.
Investing can involve risks, and different investments have different levels of risk and potential return. Therefore, it is important to understand what you are investing in before committing money.
For long-term goals such as retirement, consistent contributions over many years can be an important part of building financial resources.
Your investment decisions should take into account your goals, time horizon, financial situation, and tolerance for risk.
13. Increase Your Income When Possible
Managing expenses is important, but increasing income can also improve your financial flexibility.
You might develop new professional skills, pursue additional training, negotiate compensation when appropriate, take on freelance work, or explore other legitimate income opportunities.
When your income increases, consider directing at least part of the additional money toward savings, investments, or debt repayment rather than automatically increasing your lifestyle expenses.
14. Review Your Financial Progress
Your financial plan should not remain unchanged forever.
Review your budget, savings, debt, investments, and goals periodically. Your income or expenses may change, and your priorities may evolve.
A regular financial review can help you identify problems early and make adjustments when necessary.
You might discover that you can increase your savings rate, reduce unnecessary expenses, or redirect money toward a more important goal.
Final Thoughts
Healthy money habits can play an important role in building a stronger financial future. Creating a budget, tracking spending, saving consistently, managing debt, paying bills on time, and setting clear financial goals can help you take greater control of your money.
You do not have to change everything at once. Start with one or two habits that are realistic for your current situation and build from there.
Financial progress is often the result of consistent decisions made over time. By developing thoughtful money habits today, you can create a stronger foundation for handling expenses, reaching financial goals, and preparing for the future.