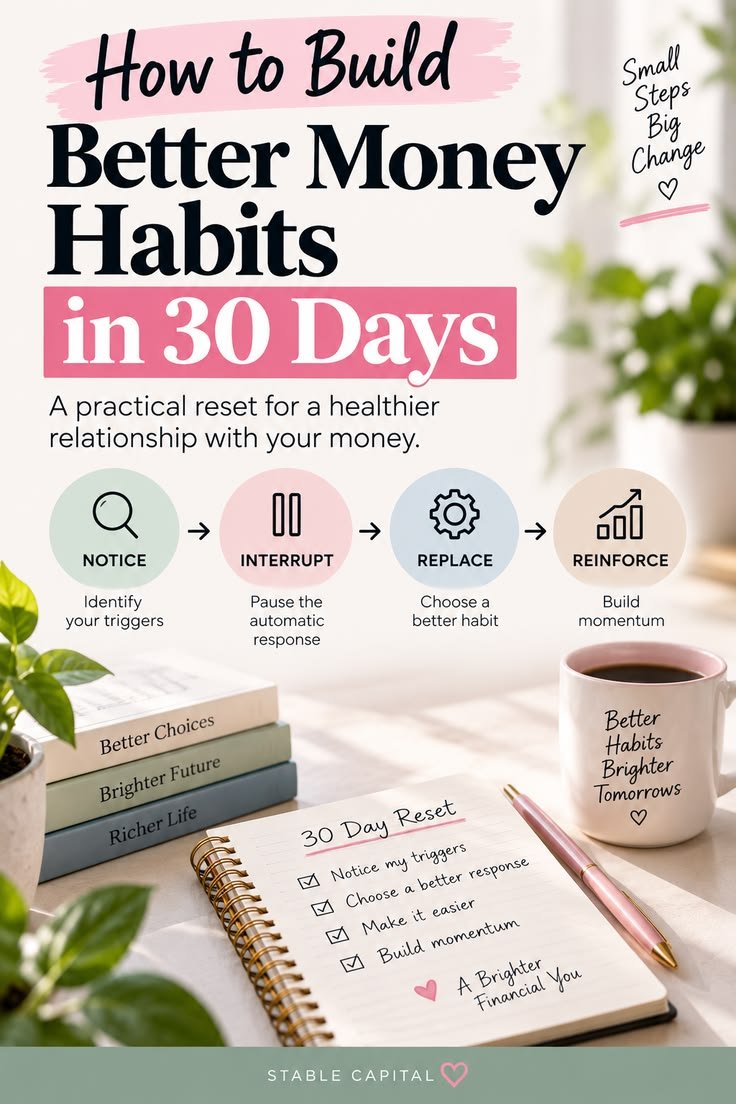

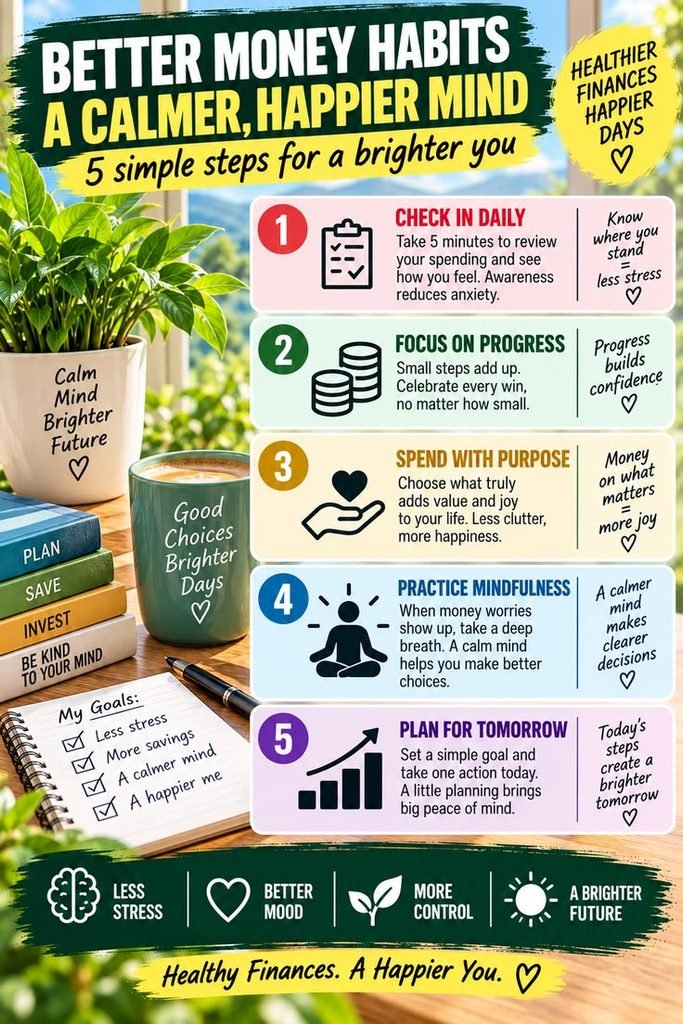
Building better money habits can make a major difference in your financial life. Earning more money can certainly help, but how you manage the money you already have is also important. Good financial habits can help you control spending, increase savings, reduce unnecessary debt, and work toward long-term financial goals.
The good news is that you do not need to completely change your lifestyle overnight. Small, consistent improvements can gradually become habits that make managing your money easier.
Whether you are trying to save your first $1,000, pay off debt, build an emergency fund, or prepare for retirement, developing better financial habits can help you move toward your goals.
1. Know Where Your Money Goes
One of the first steps toward better money management is understanding how you spend your money.
Many people know approximately how much they earn each month but do not know exactly how much they spend.
For one month, try tracking every expense.
Include:
- Rent or mortgage
- Groceries
- Restaurants
- Transportation
- Utilities
- Subscriptions
- Entertainment
- Shopping
- Debt payments
- Savings
You can use a spreadsheet, notebook, banking app, or budgeting application.
Once you see where your money goes, it becomes easier to identify spending patterns and areas that may need attention.
2. Create a Realistic Budget
A budget gives your money a purpose.
Start with your monthly take-home income and subtract your essential expenses. Then decide how much you want to allocate toward savings, debt payments, and discretionary spending.
For example, someone earning $4,000 per month might create a plan such as:
- Housing and utilities: $1,500
- Food: $500
- Transportation: $400
- Debt payments: $400
- Savings: $500
- Entertainment and personal spending: $400
- Other expenses: $300
These numbers are only an example. Your own budget should reflect your income, location, household, financial obligations, and goals.
A good budget should be realistic enough that you can actually follow it.
3. Pay Yourself First
One useful money habit is saving before spending on non-essential purchases.
Instead of waiting until the end of the month to see what is left, decide in advance how much you want to save.
For example, if you earn $4,000 per month and decide to save $400, you can move that money into savings shortly after receiving your paycheck.
This approach makes saving a regular financial priority instead of something you do only when extra money is available.
4. Build an Emergency Fund
An emergency fund can protect you from unexpected financial problems.
Unexpected expenses can include:
- Car repairs
- Medical expenses
- Home repairs
- Temporary loss of income
- Emergency travel
- Other necessary costs
Start with a small target if necessary. You could work toward $500, then $1,000, and gradually build a larger emergency reserve.
A commonly used long-term goal is to maintain several months of essential living expenses, although the appropriate amount depends on your circumstances.
5. Avoid Impulse Spending
Impulse purchases can make it difficult to reach financial goals.
Before buying something that is not essential, give yourself time to think about the purchase.
Ask yourself:
Do I actually need this?
Is it in my budget?
Can I afford it without affecting my savings goals?
Would I still want it if I waited a few days?
For larger purchases, waiting 24 hours or longer before buying can help you make a more deliberate decision.
6. Use Credit Cards Carefully
Credit cards can be useful financial tools when used responsibly, but carrying high-interest balances can become expensive.
Try to avoid treating your available credit as extra income.
If you use a credit card, keep track of your spending and understand the interest rate, fees, and payment requirements.
Paying your balance according to the card’s terms can help you avoid unnecessary interest charges.
Most importantly, do not spend more than you can realistically afford simply because your credit limit allows it.
7. Automate Your Savings
Automation can make good financial habits easier.
If your bank allows automatic transfers, you can schedule money to move from your checking account into a savings account regularly.
For example, you might automatically transfer $100 every week.
That would equal:
$100 × 52 weeks = $5,200 per year
This example assumes you can comfortably afford the transfer and maintain enough money for your essential expenses.
Automation reduces the need to remember to save every time you receive income.
8. Reduce Unnecessary Subscriptions
Monthly subscriptions can quietly become a significant expense.
Review your subscriptions and ask whether you actually use each service.
You may discover that you are paying for:
- Streaming platforms
- Fitness memberships
- Software
- Apps
- Online services
- Subscription boxes
If you are paying $15 per month for a service you rarely use, canceling it could save $180 per year.
Small savings can become meaningful when repeated over many years.
9. Make Saving Automatic When Your Income Increases
When your salary increases, it can be tempting to increase your lifestyle immediately.
For example, if your monthly income rises by $500, you might be tempted to spend the entire additional amount.
Instead, consider directing part of the increase toward savings, retirement contributions, or debt repayment.
You can still improve your lifestyle while making sure that some of your additional income strengthens your financial position.
10. Set Specific Financial Goals
A financial goal is easier to work toward when it is specific.
Instead of saying:
“I want to save more money.”
Try:
“I want to save $3,000 for an emergency fund within the next 12 months.”
A specific goal tells you how much you need and gives you a time frame.
You can then calculate a monthly target.
For example:
$3,000 ÷ 12 months = $250 per month.
Breaking a large goal into smaller steps can make it feel more achievable.
11. Learn Before Making Major Financial Decisions
Good money habits include learning before making important financial decisions.
Before taking out a loan, opening an investment account, purchasing insurance, or making a major purchase, research the costs and risks.
Understand:
- Interest rates
- Fees
- Terms
- Penalties
- Potential risks
- Long-term costs
Avoid making major financial decisions simply because someone on social media recommends a particular product or investment.
12. Review Your Finances Every Month
You do not need to think about your finances every hour.
Instead, set aside time once a month to review your financial situation.
Check:
- Income
- Spending
- Savings
- Debt
- Investments
- Financial goals
Ask yourself what went well and what needs to change.
Your financial plan may need to change when your income, expenses, family situation, or financial goals change.
13. Avoid Comparing Your Finances With Other People
Social media can make it appear as though everyone else is earning more, traveling more, buying better cars, or living a more expensive lifestyle.
Remember that you usually do not see the full financial picture.
Someone may appear wealthy while carrying significant debt.
Instead of comparing your finances with someone else’s lifestyle, focus on your own progress.
If you saved $1,000 this year and had no savings previously, that is meaningful progress.
14. Make Good Habits Easy
The best financial habits are often the ones that require the least effort.
You can make saving easier by:
- Automating transfers
- Using separate savings accounts
- Setting spending limits
- Reviewing subscriptions
- Tracking expenses
- Setting reminders for bills
The goal is to create a financial system that helps you make good decisions without relying entirely on willpower.
Common Money Habits to Avoid
Some habits can make financial progress more difficult.
These include:
- Spending more than you earn
- Ignoring your bank statements
- Making frequent impulse purchases
- Carrying unnecessary high-interest debt
- Having no emergency savings
- Paying for unused subscriptions
- Making financial decisions based on social-media trends
- Increasing spending every time your income rises
You do not need to fix everything at once. Choose one or two habits and work on them consistently.
Final Thoughts
Building better money habits is a gradual process. You do not need a perfect financial plan or a huge income to begin.
Start by tracking your spending, creating a realistic budget, saving regularly, building an emergency fund, controlling impulse purchases, and setting clear financial goals.
As these behaviors become routine, managing your money can become less stressful and more organized.
The goal is not to stop spending money altogether. It is to make intentional decisions about your money so that your everyday choices support your bigger financial goals.
Small improvements made consistently can eventually create significant changes in your financial life.