
Bank accounts are an important part of everyday financial life. People use checking and savings accounts to receive paychecks, pay bills, transfer money, save for future goals, and manage their daily spending. However, many banking services can come with fees.
Bank fees can sometimes be confusing, especially when customers do not understand what they are paying for or how the charges can be avoided. While some fees may be associated with specific services or account features, others can result from actions such as overdrawing an account or using certain services outside the bank’s network.
Understanding why banks charge fees can help you identify unnecessary costs and choose accounts that fit your financial needs.
What Are Bank Fees?
Bank fees are charges that financial institutions may apply for certain services, transactions, account features, or situations.
The amount and type of fees depend on the bank, account, and services involved.
Common examples include:
- Monthly maintenance fees
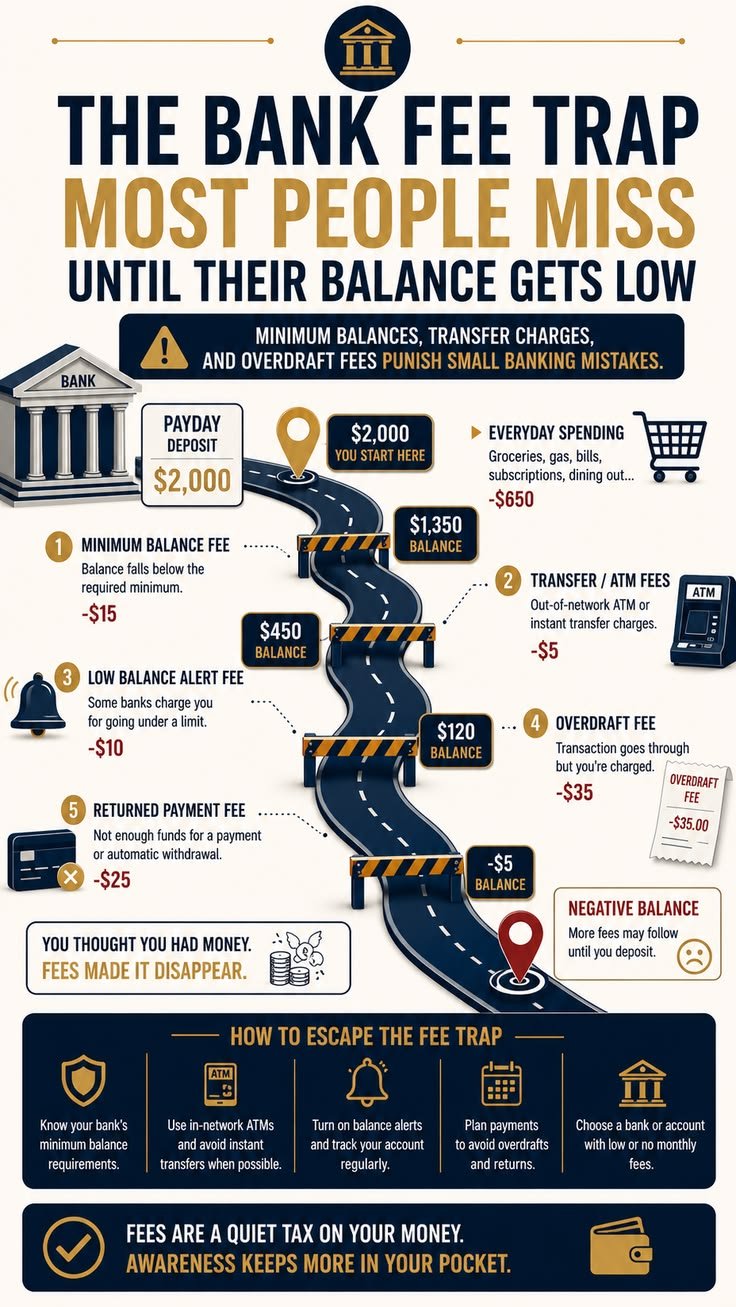
- Overdraft fees
- ATM fees
- Out-of-network ATM fees
- Wire transfer fees
- Foreign transaction fees
- Stop-payment fees
- Paper statement fees
- Excess transaction fees on certain accounts
Not every bank charges every type of fee, and some accounts have ways to avoid certain charges.
Why Do Banks Charge Fees?
Banks operate businesses that require employees, technology, physical locations, security systems, payment networks, customer service, and other resources.
Fees can help cover the costs associated with providing certain services.
For example, processing a wire transfer or maintaining specialized account features may require additional resources. A bank may charge a fee for the service rather than including its cost in every customer’s basic account pricing.
Banks can also use fees as part of their overall revenue model.
However, the specific reason for a fee depends on the type of charge and the bank’s account agreement.
Monthly Maintenance Fees
Some checking and savings accounts have monthly maintenance fees.
A bank may waive the fee if you meet certain requirements. For example, an account may offer fee-free banking if you maintain a specified balance, receive qualifying direct deposits, or meet other conditions.
Before opening an account, read the fee schedule and account terms carefully.
If you are paying a monthly fee, check whether your account provides benefits that justify the cost or whether another account might better fit your needs.
Overdraft Fees
An overdraft can occur when you spend more money than is available in your account and the bank pays or otherwise processes the transaction under its overdraft service.
Depending on the bank and account terms, this can result in a fee.
Overdraft policies vary considerably among financial institutions and account types. Some banks offer services that link a checking account to a savings account or another source of funds to help cover certain transactions.
Understanding your bank’s overdraft policies can help you avoid unexpected charges.
ATM Fees
Using an ATM outside your bank’s network may result in an ATM fee.
In some cases, both the ATM operator and your own financial institution may charge fees.
One way to reduce these costs is to use ATMs included in your bank’s network or choose an account that provides reimbursement for certain ATM fees.
Before withdrawing cash, check whether the ATM displays a fee.
Wire Transfer Fees
Wire transfers allow money to be sent electronically between financial institutions.
Banks may charge fees for sending or receiving certain wire transfers. Domestic and international transfers may also have different pricing structures.
If you regularly send money by wire, compare the fees charged by different financial institutions and understand the total cost before initiating a transfer.
Foreign Transaction Fees
Some banks or financial institutions may charge fees when customers make transactions involving foreign currencies or international merchants.
These charges can apply when traveling internationally or purchasing goods and services from businesses outside the United States.
If you travel frequently, review your account’s foreign transaction policy before your trip.
Some financial products are designed specifically for international use and may have different fee structures.
Why Reading the Fee Schedule Matters
Many people only look at an account’s interest rate or advertised benefits when choosing a bank.
However, fees can also have a meaningful impact on your finances.
Before opening an account, review the bank’s fee schedule and account agreement.
Pay attention to:
- Monthly fees
- Minimum balance requirements
- ATM fees
- Overdraft policies
- Transfer fees
- Wire fees
- Foreign transaction charges
- Account closing requirements
- Other service charges
Understanding these details can help you avoid unpleasant surprises.
How Can You Avoid Bank Fees?
One of the easiest ways to reduce banking costs is to understand the requirements associated with your account.
For example, if your bank waives a monthly fee when you receive a qualifying direct deposit, make sure you understand what qualifies.
You can also:
Use in-network ATMs: This can reduce or eliminate certain ATM charges.
Monitor your balance: Checking your account regularly can help you avoid spending more money than you have available.
Set up account alerts: Many banks allow customers to receive notifications about low balances, large transactions, or other account activity.
Choose online statements: If your bank charges for paper statements, switching to electronic statements may reduce the cost.
Compare accounts: If your current account has fees you cannot avoid, consider comparing other account options.
Are Bank Fees Always Bad?
Not necessarily.
A fee does not automatically mean that a bank account is a poor choice.
Some accounts charge fees in exchange for additional services, benefits, or features. For example, a premium account might provide services that are valuable to a particular customer.
The important question is whether the fees are reasonable for the services you actually use.
A free account may not always be the best option if it lacks features that are important to you. Similarly, paying for services you never use may not make financial sense.
How Much Can Bank Fees Cost Over Time?
Small fees can add up.
For example, suppose an account charges a $10 monthly maintenance fee. Over one year, that would amount to $120.
If you can avoid the fee simply by meeting a qualifying requirement or switching to a different account, that money could instead remain in your account or be directed toward savings.
This is why reviewing recurring banking fees can be worthwhile.
Compare Banks Before Opening an Account
Different financial institutions have different fee structures.
When comparing checking or savings accounts, consider more than the advertised interest rate.
Look at monthly fees, minimum balance requirements, ATM access, overdraft policies, online banking features, customer support, and other services you expect to use.
The right account depends on your financial habits.
Someone who frequently uses cash may prioritize convenient ATM access, while someone who rarely visits branches may prefer an online-focused account.
Final Thoughts
Banks charge fees for various reasons, including covering the costs of providing services and generating revenue. Common fees include monthly maintenance charges, ATM fees, overdraft fees, wire transfer charges, and foreign transaction fees.
Not every bank charges the same fees, and many accounts offer ways to avoid certain charges.
The best way to manage bank fees is to understand your account’s terms, monitor your transactions, use available fee-waiver options, and compare accounts when necessary.
Banking fees may seem small individually, but recurring charges can add up over time. Taking a few minutes to understand what your bank charges can help you keep more of your money and make better financial decisions.