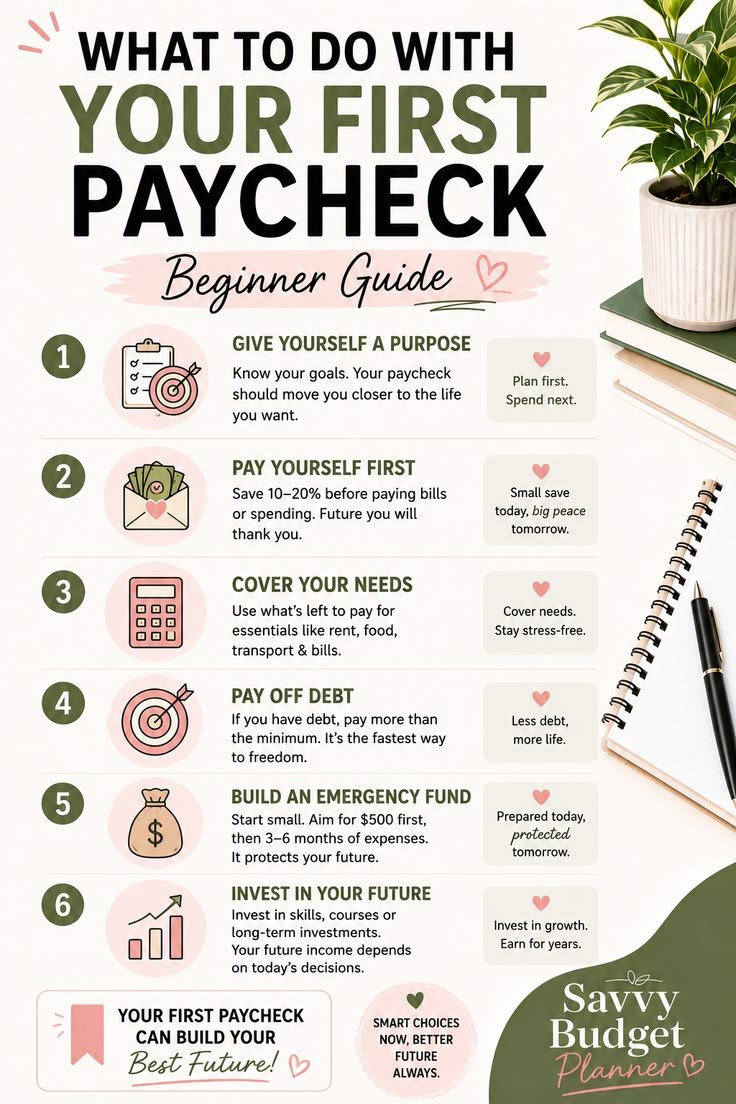

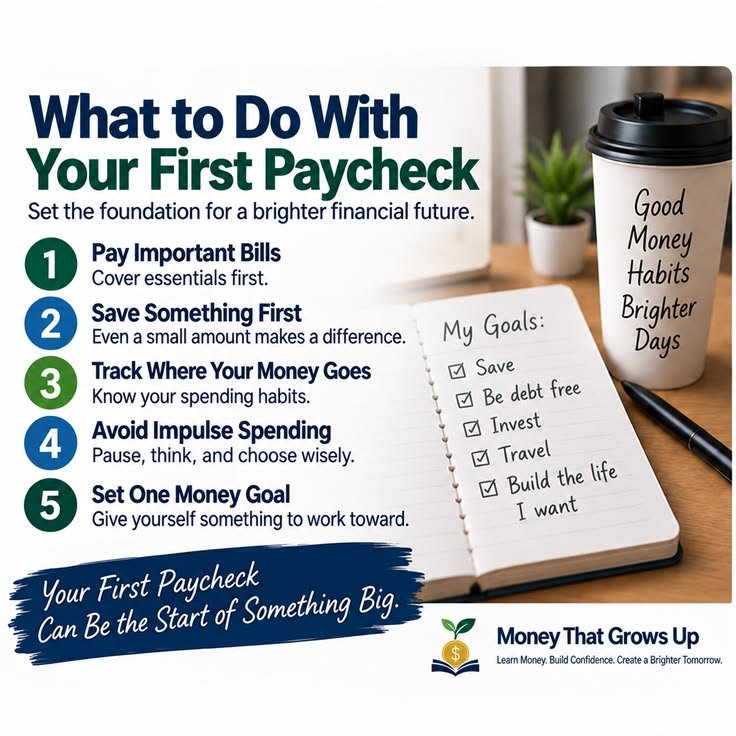
Receiving your first paycheck can be an exciting moment. After spending time studying, training, applying for jobs, and preparing for your career, finally earning your own money can feel like an important milestone.
It can also be tempting to spend your first paycheck immediately. You may want to buy new clothes, upgrade your phone, go out with friends, or purchase something you have wanted for a long time. While enjoying some of your money is perfectly reasonable, your first paycheck can also be an opportunity to establish healthy financial habits that can benefit you for years.
The way you manage your first paycheck does not have to be complicated. A few simple steps can help you build a strong financial foundation.
1. Understand Your Take-Home Pay
Before deciding what to do with your paycheck, understand how much money you actually receive.
Your salary may be different from your take-home pay because taxes, retirement contributions, insurance, and other deductions may be taken out before the money reaches your bank account.
Look at your pay statement and understand the deductions. Knowing your actual income will make it easier to create a realistic budget.
For example, if your advertised salary is $4,000 per month but your take-home pay is $3,200, your budget should be based on the $3,200 you actually receive rather than the higher gross amount.
2. Create a Simple Budget
One of the first things you can do with your paycheck is create a budget.
A budget gives every part of your income a purpose. Start by listing your essential expenses, such as rent, utilities, groceries, transportation, insurance, and debt payments.
Then consider other expenses, including entertainment, subscriptions, eating out, clothing, and hobbies.
After accounting for your expenses, determine how much you can put toward savings and other financial goals.
Your first budget does not need to be perfect. The goal is to understand your spending and create a system that you can adjust as you learn more about your financial situation.
3. Build an Emergency Fund
An emergency fund can help you handle unexpected expenses without depending entirely on credit cards or loans.
Unexpected costs can include car repairs, medical bills, urgent home repairs, or a temporary loss of income.
If you are starting with no savings, your first goal does not necessarily need to be a large amount. You could begin by setting aside a small amount from every paycheck and gradually increase your savings.
Keeping emergency savings in a separate savings account can also make it easier to avoid spending the money on everyday purchases.
4. Pay Attention to High-Interest Debt
If you already have debt, your first paycheck can be an opportunity to start managing it strategically.
Credit card balances and other high-interest debt can become expensive when they remain unpaid for long periods. Review your balances, interest rates, minimum payments, and due dates.
Make at least the required payments on time and consider putting additional money toward high-interest balances when your budget allows.
Reducing expensive debt can free up more of your future income for saving and investing.
5. Start Saving for Retirement
Retirement may seem far away when you receive your first paycheck, especially if you are young. However, starting early can give your savings more time to potentially grow.
If your employer offers a workplace retirement plan, learn how it works and whether the employer provides matching contributions.
If you have access to a retirement plan, consider contributing an amount that fits comfortably within your budget. As your income increases, you can review your contribution rate and potentially increase it.
The important lesson is to make long-term saving a regular part of your financial habits rather than something you plan to start much later.
6. Avoid Lifestyle Inflation
Getting your first real paycheck can make you feel wealthier than you were before. This can lead to lifestyle inflation, which happens when spending increases as income increases.
For example, someone might receive their first substantial salary and immediately move into a more expensive apartment, purchase a new vehicle, eat at expensive restaurants frequently, and take on additional subscriptions.
Higher income can certainly improve your quality of life, but increasing expenses too quickly can make it difficult to build wealth.
Instead, consider allowing your savings and financial goals to grow alongside your lifestyle.
7. Set Financial Goals
Your first paycheck can be the beginning of a larger financial plan.
Think about what you want your money to accomplish over the next few months, several years, and eventually decades.
Your short-term goal might be building a $1,000 emergency fund. A medium-term goal could be saving for a vehicle or home. A long-term goal could involve retirement or investing.
Writing down your goals can make them easier to track. Try to make them specific and measurable so you can see your progress.
8. Automate Your Savings
Saving becomes easier when you do not have to remember to transfer money manually every payday.
If your bank or employer allows it, consider setting up automatic transfers to your savings or investment accounts.
For example, you could arrange for a fixed amount to move into savings shortly after your paycheck arrives.
Automation can help you treat saving as a regular financial responsibility rather than something you do only when you have money left over.
9. Protect Your Financial Information
Your first paycheck is also a good reminder to take financial security seriously.
Use strong, unique passwords for financial accounts and enable two-factor authentication where available. Be cautious about suspicious emails, messages, and websites requesting banking information.
Avoid sharing sensitive financial information unnecessarily.
Protecting your accounts is an important part of managing your money because financial progress can be damaged quickly by fraud or unauthorized access.
10. Enjoy Some of Your Money
Financial responsibility does not mean you should never enjoy your paycheck.
In fact, completely eliminating entertainment and personal spending can make a budget difficult to maintain.
Consider setting aside a reasonable amount for something you enjoy. You might have dinner with friends, purchase something useful, or celebrate your new job.
The key is balance. Enjoying a portion of your income while still saving and meeting your financial responsibilities can help you create a sustainable relationship with money.
What Should You Avoid Doing With Your First Paycheck?
There are several mistakes worth avoiding.
First, try not to spend your entire paycheck simply because you have received it. Having money available does not necessarily mean you can afford every purchase.
Second, avoid taking on large new debts for unnecessary purchases. Financing an expensive car or buying costly items on credit can create financial pressure before you have established a strong financial foundation.
Finally, do not compare your spending with friends or coworkers. Everyone has different financial responsibilities, income levels, and goals.
Your financial plan should reflect your own circumstances.
A Simple First-Paycheck Strategy
A practical approach could be to divide your paycheck among several priorities:
Essential expenses: Pay for housing, food, transportation, utilities, and other necessities.
Savings: Put money toward an emergency fund and other savings goals.
Debt: Make required payments and consider paying extra toward high-interest debt.
Retirement: Contribute to an available retirement account if appropriate for your circumstances.
Personal spending: Reserve some money for entertainment and things you enjoy.
The exact percentages will depend on your income, expenses, debts, and financial goals. There is no single formula that works for everyone.
Final Thoughts
Your first paycheck is more than just money in your bank account. It is an opportunity to establish financial habits that can influence your future.
Start by understanding your take-home pay, creating a budget, building emergency savings, managing debt, and beginning long-term savings. At the same time, allow yourself some room to enjoy the money you have earned.
You do not need to become financially perfect with your first paycheck. The goal is to develop consistent habits and make thoughtful decisions as your income and responsibilities change.
A paycheck can provide more than immediate spending power. When managed carefully, it can become the foundation for financial security, future goals, and long-term financial independence.