

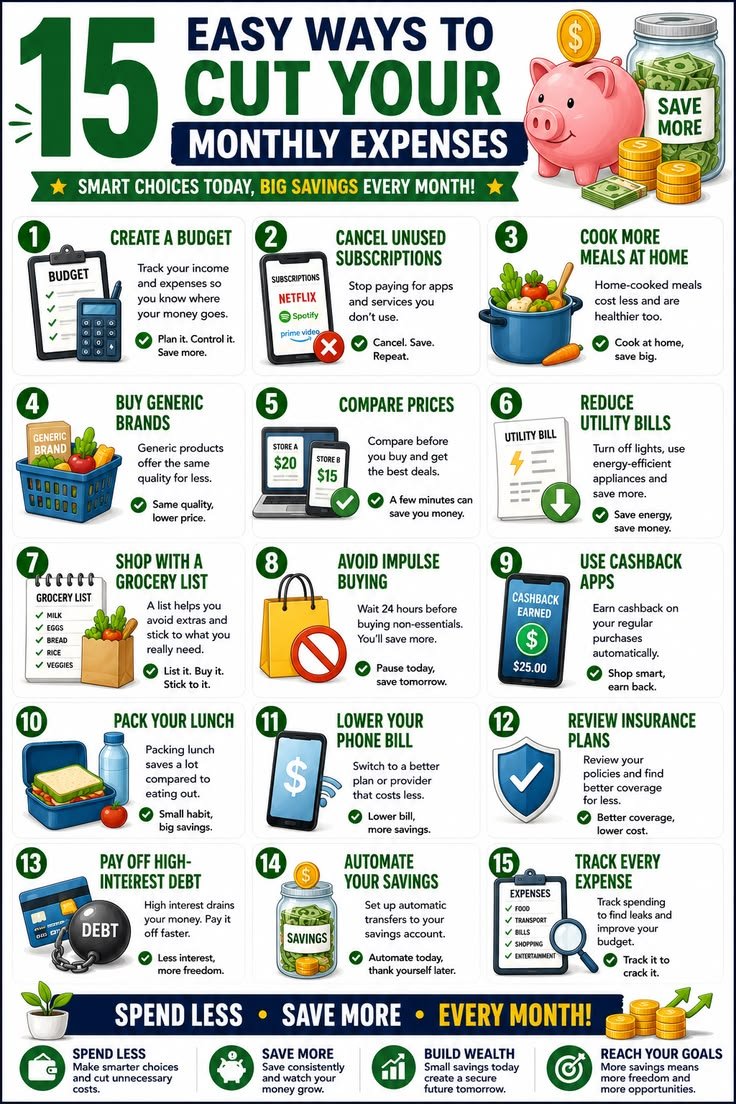
Managing monthly expenses is an important part of maintaining financial stability. When you know where your money is going, you can make better decisions about spending, saving, debt repayment, and long-term financial goals.
Many people struggle with monthly expenses because bills can quickly add up. Housing, groceries, transportation, utilities, insurance, subscriptions, debt payments, and personal spending can consume a large portion of your income.
The good news is that managing your expenses does not require eliminating everything you enjoy. Instead, it requires creating a realistic plan, tracking your spending, prioritizing important costs, and making adjustments when necessary.
1. Know Your Monthly Income
Before managing your expenses, you need to know how much money you have available.
Use your monthly take-home income rather than your salary before taxes and deductions.
For example, if your household brings home $4,500 per month, that is the amount you should use when planning your monthly spending.
If your income changes from month to month, such as with freelance or commission-based work, consider using a conservative estimate based on your recent earnings.
Knowing your available income prevents you from creating a spending plan that is unrealistic.
2. List All Your Monthly Expenses
Create a complete list of your expenses.
Start with fixed expenses such as:
- Rent or mortgage
- Car payments
- Insurance
- Student loan payments
- Phone bills
- Internet
Then list variable expenses such as:
- Groceries
- Gas
- Restaurants
- Entertainment
- Shopping
- Personal care
Do not forget smaller recurring expenses. Subscriptions and frequent small purchases can add up over time.
3. Separate Fixed and Variable Expenses
Understanding the difference between fixed and variable expenses can make budgeting easier.
Fixed expenses generally remain similar each month. Examples include rent, mortgage payments, and certain insurance premiums.
Variable expenses can change from month to month. Examples include groceries, fuel, entertainment, and restaurant spending.
Variable expenses may provide more opportunities for adjustment.
For example, if your grocery spending is regularly $600 per month, you could examine whether reducing it to $500 is realistic without compromising your household’s needs.
4. Separate Needs From Wants
Another useful strategy is dividing expenses into needs and wants.
Needs may include:
- Housing
- Food
- Utilities
- Transportation
- Healthcare
- Insurance
Wants may include:
- Entertainment
- Restaurant meals
- Hobbies
- Premium subscriptions
- Non-essential shopping
You do not have to eliminate wants. Instead, decide how much you can comfortably spend on them after your essential expenses and financial priorities are covered.
5. Create a Monthly Budget
Once you understand your income and expenses, create a monthly budget.
For example, someone bringing home $4,500 per month might create a plan such as:
| Category | Example Amount |
|---|---|
| Housing | $1,500 |
| Food | $550 |
| Transportation | $450 |
| Utilities | $300 |
| Insurance | $250 |
| Debt payments | $400 |
| Savings | $450 |
| Personal spending | $250 |
| Other expenses | $350 |
These figures are only examples. Your actual budget should reflect your income, location, household size, and financial obligations.
6. Track Your Spending
Creating a budget is only the beginning.
You also need to track your actual spending.
You can use:
- A spreadsheet
- A budgeting app
- Your bank’s financial tools
- A notebook
- A simple phone application
At the end of each week, compare your actual spending with your budget.
If you planned to spend $400 on groceries but spent $500, identify what caused the difference.
Tracking helps you find patterns that may otherwise go unnoticed.
7. Reduce Unnecessary Recurring Expenses
Recurring expenses deserve special attention because they continue month after month.
Review your:
- Streaming services
- Gym memberships
- Apps
- Software subscriptions
- Premium memberships
- Delivery services
- Other automatic payments
If you are paying $40 per month for services you rarely use, canceling or reducing them could save $480 per year.
Even relatively small reductions can become meaningful when maintained over time.
8. Plan Your Grocery Spending
Food is an essential expense, but there may be ways to manage the cost.
Before going grocery shopping:
- Create a meal plan
- Make a shopping list
- Compare prices
- Check what you already have at home
- Reduce food waste
- Consider store brands when appropriate
Avoid shopping without a plan if you tend to make impulse purchases.
You can also establish a weekly grocery limit that fits within your monthly budget.
9. Control Impulse Purchases
Impulse purchases can make monthly budgeting difficult.
Before buying something that is not essential, consider waiting before making the purchase.
Ask:
Do I need this?
Is it in my budget?
Will buying it affect another financial goal?
Would I still want it after waiting a day or a week?
A short waiting period can help you distinguish between something you genuinely need and something you simply want at that moment.
10. Manage Your Debt Payments
Debt payments can take up a significant portion of monthly income.
Make a list of your debts and include:
- Current balance
- Interest rate
- Minimum payment
- Due date
Pay at least the required amount according to the terms of each debt, while considering a strategy for paying down high-interest balances.
Reducing expensive debt can eventually free up money that can be redirected toward savings and other goals.
11. Build an Emergency Fund
An emergency fund can make monthly finances more resilient.
Unexpected expenses such as car repairs, medical costs, or temporary income loss can disrupt even a carefully planned budget.
Start with a manageable goal, such as $500 or $1,000, and gradually build toward several months of essential expenses if your circumstances allow.
Keeping emergency savings separate from everyday spending can make it less tempting to use the money for non-essential purchases.
12. Automate Bills and Savings
Automation can simplify monthly money management.
You may be able to schedule:
- Bill payments
- Savings transfers
- Retirement contributions
- Debt payments
For example, automatically transferring $200 per month into savings would add up to $2,400 over a year, assuming you maintain the transfer.
Make sure automatic payments and transfers are timed appropriately and that enough money is available in your account.
13. Prepare for Irregular Expenses
Not every expense happens every month.
You may have annual or occasional expenses such as:
- Car maintenance
- Insurance premiums
- Holiday spending
- Property taxes
- Medical expenses
- Home repairs
- Annual memberships
Estimate these costs in advance when possible.
If you expect to spend $1,200 on an annual expense, setting aside $100 per month can help spread the cost across the year.
14. Look for Ways to Lower Large Expenses
Small expenses matter, but larger recurring costs can have an even greater impact on your budget.
Consider reviewing:
- Housing costs
- Transportation
- Insurance
- Debt interest
- Phone plans
- Internet plans
For example, reducing a monthly expense by $150 would save $1,800 per year.
You may not be able to change every major expense immediately, but identifying your largest costs helps you understand where the biggest opportunities may exist.
15. Give Every Dollar a Purpose
One useful budgeting habit is deciding where your income should go before you spend it.
Your money can be assigned to:
- Essential bills
- Food
- Transportation
- Debt
- Savings
- Retirement
- Entertainment
- Other financial goals
This approach can help you avoid spending money impulsively and discovering later that you do not have enough for important bills.
16. Review Your Expenses Every Month
Your budget should change when your financial circumstances change.
At the end of each month, review:
- Total income
- Total spending
- Savings
- Debt payments
- Unexpected expenses
- Progress toward financial goals
Ask yourself:
Where did I overspend?
Which expenses can I reduce?
Did I save enough?
Are my financial goals still realistic?
Use the answers to improve next month’s plan.
A Simple Monthly Expense Management Plan
You can start with these steps:
Step 1: Calculate your take-home income.
Step 2: List all fixed and variable expenses.
Step 3: Separate needs from wants.
Step 4: Create a realistic monthly budget.
Step 5: Track your spending.
Step 6: Reduce unnecessary recurring expenses.
Step 7: Manage debt carefully.
Step 8: Build emergency savings.
Step 9: Prepare for irregular expenses.
Step 10: Review and adjust your budget every month.